Browse

Log in / Register
 Share


An estate home is a large, high-value property, often situated on a substantial piece of land, that distinguishes itself from a standard single-family house through its scale, premium amenities, and unique market considerations. For buyers, understanding that an estate home represents a significant long-term investment in a luxury lifestyle, rather than just shelter, is the fundamental takeaway. This distinction impacts everything from the initial purchase process to ongoing maintenance costs and potential for resale.
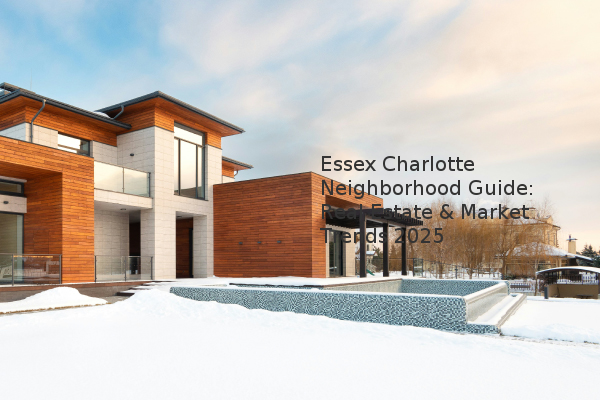
The term "estate home" lacks a strict legal definition but is a widely recognized classification in the real estate industry. It typically refers to a property that exceeds the norms of a standard house in several key areas. Size is a primary factor, with estate homes often boasting 5,000 square feet or more of living space. However, square footage alone isn't enough. These properties are usually situated on extensive, well-landscaped grounds, frequently one acre or larger, offering a high degree of privacy. The presence of high-end, custom-built features is another hallmark, such as gourmet kitchens with professional-grade appliances, dedicated entertainment spaces like home theaters or wine cellars, and resort-style outdoor amenities including pools, guest houses, and expansive patios. The construction quality and materials are typically superior, emphasizing durability and architectural detail.
Purchasing an estate home involves a more complex and nuanced process compared to a typical residential transaction. The pool of potential buyers is smaller, which means properties can sit on the market longer, sometimes leading to more flexible negotiation opportunities. It is highly advisable to work with a real estate agent who specializes in luxury properties, as they possess the specific market knowledge and network required. Financing an estate home can also be different. While some buyers may use a jumbo mortgage—a type of loan that exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA)—others may opt for alternative financing structures or purchase with cash. A thorough property inspection is even more critical, as the complex systems and custom features can entail significant future expenses if not properly vetted.
Owning an estate home comes with a distinct set of ongoing financial responsibilities that extend far beyond a standard mortgage payment. Property taxes are a major consideration. Due to the high value of the home and land, annual property tax bills can be substantial. It's crucial to research the local tax rates and understand how assessments are conducted. Additionally, maintenance and operational costs are significantly higher. The upkeep of large lawns, swimming pools, sophisticated security systems, and high-end appliances requires a dedicated budget. Homeowners insurance for an estate home is also a specialized product, often called a "high-value" or "luxury" policy, designed to cover the cost of replacing custom features and high-end finishes. Prospective buyers should factor in these recurring costs, which can easily amount to tens of thousands of dollars annually.
Table: Estimated Annual Costs for a $1.5 Million Estate Home
| Cost Category | Estimated Annual Range |
|---|---|
| Property Taxes | $15,000 - $30,000+ |
| Utilities (electric, water, gas) | $7,000 - $15,000 |
| Landscaping & Pool Maintenance | $5,000 - $20,000 |
| Homeowners Insurance | $4,000 - $10,000 |
| Routine Repairs & Upkeep | $5,000 - $15,000 |
The investment potential of an estate home is different from that of a standard residential property. While location remains a key driver of value, estate homes are often considered "niche" assets. Their value appreciation may not always mirror the broader housing market, as it is more susceptible to fluctuations in the high-end luxury sector. They are not typically purchased as short-term, high-yield investments but rather as long-term holdings and lifestyle choices. Resale can take longer due to the limited buyer pool. Therefore, the primary return on investment should be viewed as the enjoyment of the property itself, with financial gains being a potential secondary benefit over a long horizon.
Prospective buyers should approach an estate home purchase with a clear understanding of the lifestyle commitment and financial obligations involved. Key advice includes securing a specialist real estate agent, obtaining realistic cost estimates for maintenance and taxes, and prioritizing a comprehensive home inspection. While an estate home offers an unparalleled living experience, it is a decision that requires thorough due diligence and a long-term financial strategy.