Browse

Log in / Register
 Share

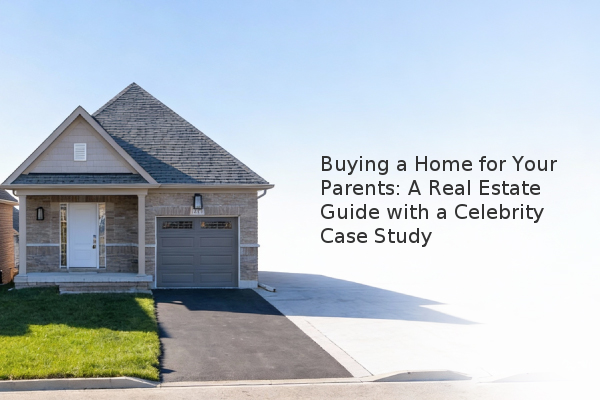
Buying a home for your parents is a significant financial and emotional milestone. This guide explores the key considerations, from financing and property selection to legal implications, using a well-known celebrity purchase as a practical case study. Based on our experience assessment, successful execution requires careful planning around budget, suitability, and ownership structure to ensure the gift serves its intended purpose.
The decision involves more than just the purchase price. Primary considerations include the parents' long-term needs, the buyer's financial health, and the legal framework of the transfer. You must assess the property's single-level layout for aging in place, proximity to healthcare, and overall maintenance requirements. Financially, the buyer needs to determine if they will gift the entire amount or secure a mortgage, which impacts their debt-to-income ratio. Legally, clarifying title ownership—whether solely in the parents' names, in the buyer's name, or jointly—affects future property taxes, liability, and inheritance planning.
Financing a home for parents typically follows one of two paths. The first is a cash purchase, which simplifies the transaction but requires substantial liquid assets. The second is obtaining a mortgage. If the adult child is the borrower, lenders will evaluate their creditworthiness and existing debts based on standard criteria. It's crucial to note that if the parents will be making the payments, this may require a "non-occupant co-borrower" loan structure. Gift letters are mandatory if you are providing funds for a down payment on a mortgage in your parents' names, formally stating the money does not need to be repaid.
A practical example involves a property in the Sherman Oaks neighborhood of Los Angeles. In 2013, a developer purchased a modest, existing home for $710,000. The original structure was considered a tear-down, a term for a property where the land value exceeds the value of the building, making demolition and new construction the most financially viable option. The developer built a new 4,672-square-foot Spanish-style home featuring four bedrooms and 4.5 bathrooms, which sold in 2015 for $1.7 million. This case highlights the value of location and lot size in real estate, where a large corner lot in a desirable area can justify the cost of a custom build.
The tax implications are a critical component. In the United States, the IRS allows an annual gift tax exclusion ($18,000 per recipient for 2026). If the purchase price exceeds this amount and the property is legally gifted to the parents, the excess may apply against the buyer's lifetime gift and estate tax exemption ($13.61 million for 2026). However, if the buyer retains ownership and allows the parents to live there rent-free, the arrangement may have different tax consequences. Consulting with a tax professional is highly recommended to navigate these rules.
Beyond finances, the property's safety and suitability are paramount. This includes evaluating the neighborhood's safety record and investing in a modern home security system. The home’s layout should be future-proofed, considering potential mobility issues. Furthermore, a thorough home inspection is non-negotiable to identify any needed repairs in the plumbing, electrical systems, or foundation before finalizing the purchase, ensuring the home is a safe and sound investment.
Purchasing a home for your parents is a rewarding endeavor that demands a strategic approach. Key steps include securing financing responsibly, selecting a property that meets long-term needs, and understanding the legal and tax consequences. The most critical factor is ensuring the decision is sustainable for your financial future while providing a secure and comfortable home for your family.