Browse

Log in / Register
 Share

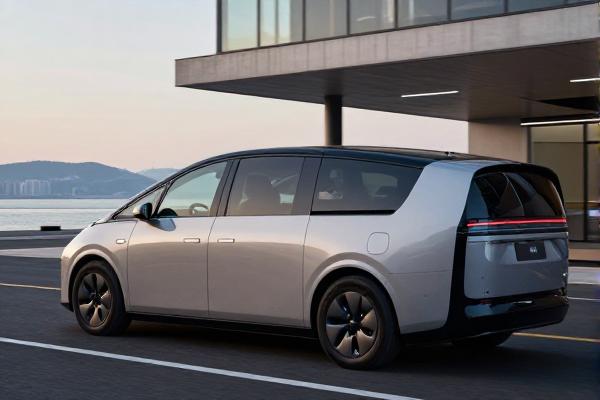
July 20, 2024 — A tectonic shift is underway in the global automotive sector, fundamentally altering how cars are designed, built, and experienced. For the United States, this evolution centers on the rise of software-defined vehicles (SDVs), where code governs everything from performance to safety, creating both unprecedented opportunities and urgent challenges for American manufacturers, policymakers, and engineers.
The numbers tell a compelling story. In 2023, electric vehicle (EV) sales in the U.S. surpassed 1.2 million units, accounting for over 9% of new car registrations, with projections indicating a climb to 40% by 2030, according to the International Energy Agency. These figures are often framed as an electrification triumph, but they mask a deeper reality: every modern EV is, at its core, a software-driven machine. Features like advanced driver-assistance systems (ADAS), over-the-air (OTA) updates, and cloud-integrated diagnostics are no longer luxury add-ons but standard expectations in mid-market models. The U.S. SDV market is poised to expand at a compound annual growth rate of over 18% through 2030, driven by consumer demand for smarter, updatable cars that evolve long after purchase.
Competition in the automotive world has been rewritten. For decades, American dominance relied on hardware prowess—engine power, manufacturing scale, and supply chain efficiency. While these remain critical, they are no longer enough. Today, a vehicle’s value is increasingly defined by its software ecosystem, enabling manufacturers to roll out enhancements like improved battery management, refined autonomous features, or new infotainment options via OTA updates. This transforms the product lifecycle from a static endpoint at delivery to a dynamic, ongoing relationship with customers. Major U.S. automakers, from General Motors to Ford, are restructuring their R&D divisions around agile software platforms, shortening development cycles from years to months and prioritizing skills in embedded systems and real-time data analytics.
The United States is uniquely positioned to lead this transformation, thanks to its deep reservoirs of engineering talent and innovation infrastructure. American expertise in embedded software, AI algorithm development, EV battery technology, and cloud computing aligns perfectly with the demands of the SDV era. Global automakers increasingly view the U.S. not just as a sales hub but as a strategic partner for solving complex software challenges, from cybersecurity architectures to vehicle-to-everything (V2X) communication systems. This shift elevates America’s role from manufacturing executor to intellectual co-author in the global automotive value chain, fostering high-value jobs and domestic innovation.
However, significant hurdles demand immediate attention. First, an interdisciplinary talent gap persists: while the U.S. excels in producing software engineers and mechanical specialists, the SDV revolution requires hybrid professionals fluent in both domains—those who can navigate ISO 26262 safety standards while deploying agile code. Scaling this workforce necessitates closer collaboration between industry and academia, with updated engineering curricula that blend hardware and software disciplines. Second, cybersecurity has emerged as a safety-critical imperative. Connected vehicles present expansive attack surfaces; a breach could compromise not only data but also critical functions like braking or steering. The industry must embed security-by-design principles into vehicle architectures from the outset, treating them with the same rigor as crash-test standards rather than as an afterthought. Third, validation processes must accelerate to match software’s pace. Traditional hardware testing timelines are ill-suited for rapid OTA deployments, necessitating investment in virtual simulation, digital twins, and AI-driven testing platforms to maintain safety without stifling innovation.
Policy frameworks must evolve in lockstep with technological advances. While U.S. regulations have encouraged EV adoption through incentives like the Inflation Reduction Act, the SDV era demands more nuanced governance. Clear federal guidelines are needed for OTA updates at scale, liability protocols for autonomous driving incidents, and enforceable cybersecurity benchmarks for connected vehicles. Additionally, policies should incentivize retaining intellectual property from domestically developed SDV platforms on American soil, ensuring long-term economic benefits. Countries that establish such clarity first will attract the engineering investments shaping next-generation mobility, and the window for U.S. leadership is narrowing rapidly.
Exclusive Insight: A recent analysis by the Center for Automotive Research highlights that U.S. automakers are investing over $50 billion in software and EV development through 2025, with a focus on securing domestic supply chains for critical components like semiconductors and battery cells. This push aligns with the Biden administration’s broader efforts to bolster tech sovereignty, positioning the U.S. to mitigate reliance on foreign software stacks and foster homegrown SDV innovations.
Ultimately, America’s automotive sector faces a generational inflection point. The global race for automotive leadership now hinges on who engineers the smartest, most secure, and most adaptable vehicles—not merely who manufactures them cheapest. The U.S. possesses the talent, scale, and entrepreneurial culture to succeed, but realizing this potential requires swift alignment among OEMs, suppliers, policymakers, and educators. As the code powering tomorrow’s cars is being written, the defining question remains: Will the United States seize the pen to author its own automotive future?