Browse

Log in / Register
 Share


A Gateway Mortgage is a term used to describe the initial mortgage loan that serves as a primary means of financing a home purchase, effectively acting as the "gateway" to homeownership. In 2026, understanding this crucial financial instrument is the first step for any prospective buyer. This guide provides an objective overview of what a gateway mortgage entails, its common types, and the fundamental process of securing one, based on current lending standards and market data.
A mortgage is a legal agreement where a lender provides funds to a borrower to purchase real estate, with the property itself serving as collateral for the loan. The borrower agrees to repay the loan over a set period, typically 15 or 30 years, with interest. The gateway mortgage is often the largest and most significant debt an individual will take on. Key components include the principal (the original loan amount), interest, and often property taxes and homeowner's insurance, which are frequently bundled into a monthly payment.
When you apply for a gateway mortgage, lenders assess your financial profile through a process called underwriting. This evaluation determines your loan eligibility and interest rate, heavily influenced by your credit score, debt-to-income (DTI) ratio, and down payment amount. A higher credit score and a larger down payment generally lead to more favorable loan terms.
Several mortgage products are prevalent in the current market, each with distinct features. The right choice depends on your financial situation and homeownership goals.
The following table compares the key characteristics of these common gateway mortgage types for 2026:
| Mortgage Type | Government-Backed? | Typical Minimum Down Payment | Key Eligibility Factor |
|---|---|---|---|
| Conventional | No | 3% - 20% | Strong credit history |
| FHA Loan | Yes (FHA) | 3.5% | Minimum credit score (e.g., 580 for 3.5% down) |
| VA Loan | Yes (VA) | 0% | Military service eligibility |
| USDA Loan | Yes (USDA) | 0% | Income and property location |
The journey to securing your gateway mortgage involves a series of structured steps. Being prepared can streamline the experience.
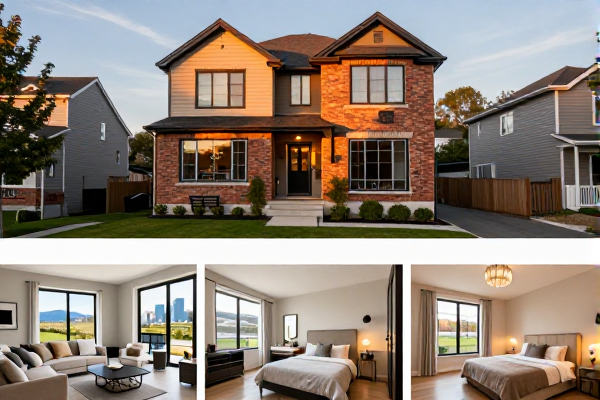
Based on our experience assessment, common pitfalls include making large purchases on credit during the loan process, which can affect your DTI ratio and credit score, and not shopping around with multiple lenders to compare interest rates and fees. It's also crucial to understand all the costs involved, not just the monthly principal and interest payment. Title insurance, which protects the lender and owner against ownership disputes, and origination fees are significant parts of closing costs that buyers should anticipate.
To navigate the gateway mortgage process effectively in 2026, prospective homebuyers should focus on three key actions: first, obtain a formal pre-approval to understand your true budget; second, compare loan estimates from at least three different lenders; and finally, maintain financial stability throughout the entire home-buying journey to ensure a smooth closing process.