Browse

Log in / Register
 Share


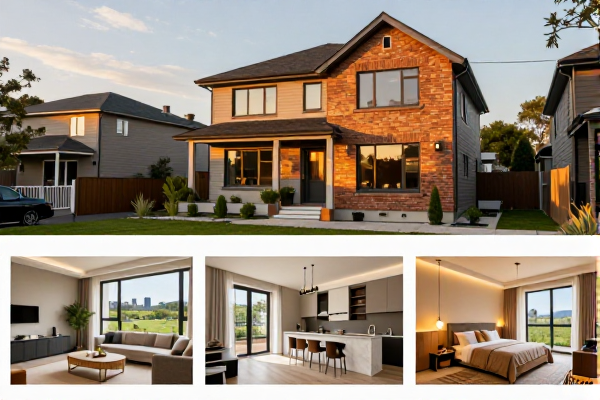
In 2026, opting for new home construction offers buyers a path to a personalized, energy-efficient, and low-maintenance property, but requires a clear understanding of timelines, financing, and the builder selection process. Unlike purchasing an existing home, building allows for customization from the floor plan to the finishes, though it often comes with a higher upfront cost and a longer timeline before move-in. This guide provides an objective overview of what to expect when considering a newly built home.
The most significant benefit of new home construction is customization. Buyers can work with the builder to select layouts, materials, and features that match their lifestyle. Furthermore, new builds adhere to modern building codes and incorporate advanced materials, leading to superior energy efficiency. This translates to lower utility bills, a reduced carbon footprint, and increased comfort. New homes also typically come with builder warranties that cover major structural elements and systems for a set period, providing peace of mind against immediate repair costs.
As of 2026, data indicates that the base price per square foot for a new single-family home often exceeds that of a comparable existing home. This premium covers modern design, current material costs, and higher labor expenses. However, this initial cost must be weighed against long-term savings. For example, the energy savings from modern HVAC systems, insulation, and windows can be substantial. Below is a simplified cost comparison for a 2,500-square-foot home in a typical suburban market.
| Cost Component | New Construction (Estimated) | Existing Home (Estimated) |
|---|---|---|
| Base Price | $450,000 - $600,000 | $400,000 - $550,000 |
| Estimated Annual Energy Costs | $1,200 - $2,000 | $2,400 - $3,600 |
| Year 1 Major Repairs | Covered by Warranty | $5,000 - $15,000 (Potential) |
Note: These figures are illustrative and vary significantly by location, lot choice, and customization level. Land acquisition costs are separate.
The process begins long before ground is broken. First, you must secure financing. A construction-to-permanent loan is a common financing vehicle that covers the building costs and then converts into a standard mortgage upon completion. Next, selecting a reputable builder is critical; verify their license, insurance, and portfolio of past projects. Once under contract, the phases typically include site preparation and foundation, framing, installation of major systems (electrical, plumbing), interior finishing, and final inspections. The entire process can take anywhere from 10 to 16 months, depending on complexity and weather.
The most frequent challenges involve timeline delays and budget overruns. Delays can stem from supply chain issues for materials, adverse weather, or permit approval hold-ups. Budget overruns, often called change orders, occur when the buyer requests upgrades or alterations after the initial contract is signed. These changes can significantly increase the final cost. It's essential to have a contingency fund of 10-15% of the total project cost to accommodate unforeseen expenses. Thoroughly reviewing the contract and understanding what is included in the base price is a crucial step in avoiding surprises.
To navigate new home construction successfully, prioritize selecting an experienced and transparent builder, secure appropriate financing early, and maintain a realistic budget with a healthy contingency fund. While the journey is more complex than buying an existing home, the result is a property tailored to your specific needs with the benefits of modern technology and efficiency.