Browse

Log in / Register
 Share

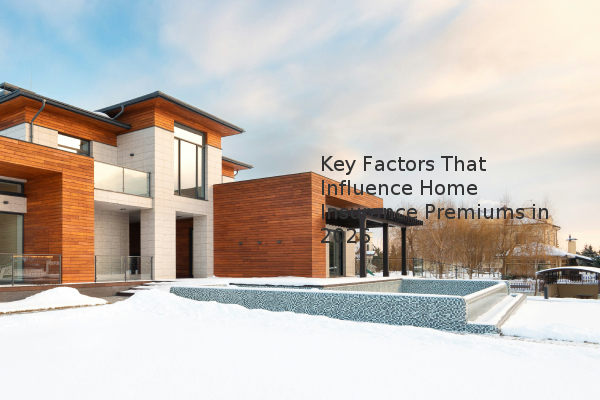
Understanding the key factors that influence your home insurance premium is the first step to securing adequate coverage at a manageable cost. Your home's location, replacement cost, age, and specific safety features are the primary determinants of your insurance rate. By proactively addressing these factors, such as by improving your home's safety systems or choosing a higher deductible, you can potentially lower your annual insurance expenses.
Your ZIP code is one of the most significant factors an insurance company considers. Premiums are calculated based on regional data, including historical claims for theft, vandalism, and fire. Homes in neighborhoods with lower crime rates typically benefit from lower premiums. Conversely, if your property is located in an area prone to natural disasters—such as hurricanes, tornadoes, or wildfires—you can expect to pay a higher rate. Based on our experience assessment, homeowners in high-risk zones may pay twice as much as those in low-risk areas. The proximity to emergency services also matters; being within a five to ten-mile radius of a fire station can lead to savings of up to 5%.
A critical factor is your home's replacement cost, which is the estimated amount to rebuild the home from the ground up, not to be confused with its market value. This cost is influenced by the home's square footage, construction materials, and the quality of key systems like HVAC and electrical. Most mortgage lenders require dwelling coverage that meets 100% of the replacement cost. It is wise to consult with a local builder to ensure your coverage is adequate, as insurer estimates can sometimes fall short. Opting for extended replacement cost coverage, which can cover up to 125% of your dwelling limit, provides an additional layer of financial protection.
Older homes often cost more to insure. The age of major systems, such as plumbing and electrical, can present a higher risk for claims. Outdated systems are more susceptible to failure, which can lead to water damage or electrical fires. Furthermore, features like original wooden floors or custom moldings require specialized labor and materials to replace, increasing the potential repair costs. Regularly maintaining these systems and updating them when necessary can not only improve safety but also make your home more attractive to insurers.
Specific amenities, while enjoyable, can increase your liability risk. Swimming pools and trampolines are considered "attractive nuisances" that raise the likelihood of injury on your property. This risk falls under your policy's liability coverage, which protects you if someone is injured on your premises. Most standard policies include a baseline of $100,000 in liability coverage, but you should adjust this amount based on your assets and potential risk exposure. Installing safety features like pool fences and securing trampolines can help mitigate this risk.
To effectively manage your home insurance costs, focus on factors within your control. Consider increasing your deductible, which can lower your premium. Improve your home's safety with modern alarm systems and automatic water shut-off valves. Maintaining a strong credit score is also beneficial, as it can lead to significant savings. Regularly review your policy with your insurance agent to ensure your coverage reflects your home's current value and your personal needs, ensuring you are neither over-insured nor under-protected.